
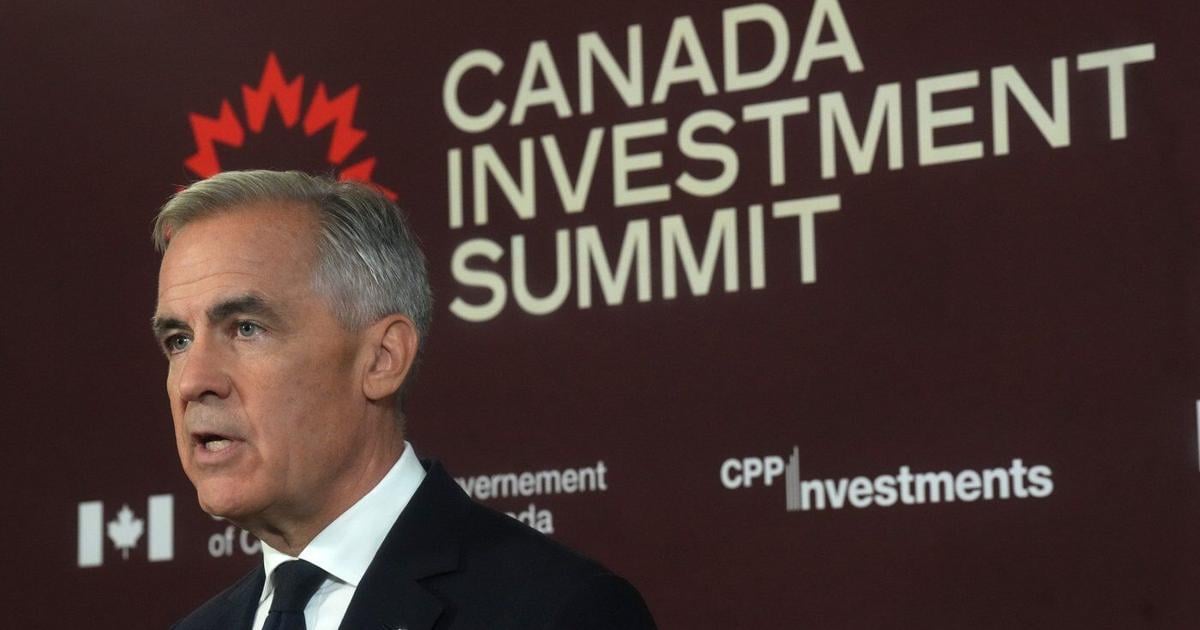
TORONTO – A Liberal and a Conservative prime minister book-ended the final day of Canada’s first-ever investment summit, each making their pitch to global investors for help fulfilling an ambitious capital agenda.
Prime Minister Mark Carney spent much of Tuesday trying to sweeten the deal for prospective investors. He announced a package of measures that included offering preferential tax measures for businesses who invest in capital and unveiled a plan to open Canada’s four major airports to private investment.
The two-day summit in Toronto — a gathering of hundreds of domestic and global executives with trillions of dollars collectively in assets under management — sought to address both historic and fresh concerns about Canada’s investment climate.
Canadian officials and business leaders were trying to buck the country’s reputation as a tough place to earn a return and replace it with a message to the world that Canada is “open for business.” That phrase rang through numerous panels, speeches and press conferences on Tuesday.
They were also pushing back against fears that a recent rupture with the United States was a death knell for Canada’s economy.
Former Prime Minister Stephen Harper tackled the U.S. concerns head-on in a speech to close-out Tuesday’s programming.
Harper, who also spoke in his capacity as board chair of the Alberta pension plan’s investment arm, said he felt Canada’s negotiating team had “no choice” but to walk away from the table with the United States a few weeks earlier. The two North American neighbours have been embroiled in fresh tariff disputes ever since.
But Harper urged Canada to lean into the disruption, particularly when it comes to resource extraction and efforts to turn the country into an “energy superpower.”
He said this is “an opportunity to realize our true potential as a country, which I believe, to be frank, we have come nowhere close to achieving.”
Harper congratulated the federal government on recent moves to fast-track project approvals, but said there was more work to be done.
Carney, who kicked off the day’s event with a keynote speech, said Tuesday that while Canada is “ahead on incentives” in the race with the United States for investment, it still has a lot of ground to make up.
The government unveiled a landmark tax reform policy to expand and make permanent immediate expensing — a tool that encourages businesses to make capital investments by allowing them to write off an investment’s full cost in its first year of use.
Ottawa said that will have the effect of lowering the marginal effective tax rate, or MER, to 6.4 per cent from 13 per cent. The MER is an industry standard for how competitive a jurisdiction is for business investment.
U.S. President Donald Trump moved to sharply lower the United States’ own marginal effective tax rate with the One Big Beautiful Bill Act passed last year. According to the Canadian government’s calculations, that rate now stands at 16.9 per cent south of the border.
Carney defended the move when asked by The Canadian Press whether the change offers only a short-term competitive edge against other countries, which might reduce their own tax rates in response.
“The incentive for companies to invest in Canada is twice as high as it is in the United States,” Carney said, referring to the tax measure.
“If we’re in a race … we’re ahead on the incentives, but we have ground to catch up. And what does this mean for Canadians and catching up to that ground? It means more jobs. It means a stronger country. It means more resilience, more independence, more sovereignty.”
Ottawa pegged the cost of the expanded deduction at $36 billion over five years.
Carney also announced Tuesday that the federal government will balance the operating side of its budget in 2027, a year earlier than planned. The Liberals are expected to continue running deficits on capital spending.
The prime minister drew praise from the corporate community on Tuesday for his efforts to stimulate investment in Canada after a long period of stagnant business spending on capital.
But not everyone is enthusiastic about offering tax breaks to businesses or opening public infrastructure to privatization.
The summit has been criticized by some Indigenous leaders, environmental groups and union leaders who said they worry about the future of public services, pipelines and arms manufacturing in Canada.
Organizers behind a protest march outside the investment summit in Toronto on Monday said in a news release that Tuesday’s announcements validated their warnings about a “fire sale” of Canada’s assets.
“This is not nation-building; it is a corporate asset grab. The federal government is setting up a rigged system where the public absorbs all the financial, environmental, and operational risks while private capital extracts all the profit,” the group said in a statement on Tuesday.
Conservative Leader Pierre Poilievre told reporters at a news conference in Vancouver Tuesday that he was happy Carney was holding an investment summit but said he wanted to see results for Canadians.
Carney said the federal government will introduce legislation during the fall session of Parliament that will expand Ottawa’s “one project, one review, one year” framework to include infrastructure proposals beyond those designated as major, “nation-building” projects.
He said the government will not compromise its high standards for projects.
“Speed, certainty, predictability themselves are competitive advantages. Investors should know that when Canada says it wants something built, Canada will get it built,” Carney told attendees at the summit.
Jon Gray, a panellist at the investment event and president of the Blackstone asset management group, told the crowd at the summit that Canada had been a “sleeping giant” for a long time but now appears to be waking up.
“We’re now at a moment where Canada’s really focused on its economic independence, and at the same time, this massive infrastructure is needed for the future,” he said.
“I think the potential growth rates here are much higher than most people would expect.”
Some of Canada’s biggest banks, insurers and pension funds took the summit as an opportunity to announce billions of dollars of investment and financing intentions in the years to come. Carney has set an audacious goal of attracting $1 trillion in investment over the next five years.
It won’t be immediately clear whether the investment summit has changed minds enough to boost foreign capital flows into Canada.
The federal government, premiers and private sector leaders were pitching dozens of projects in sectors such as energy, critical minerals, artificial intelligence and defence over the past two days, but those decisions will likely be borne out over months and years.
B.C. Premier David Eby suggested in a scrum with reporters on Tuesday that some investors might prefer to see Ottawa create a new fund for Canadian infrastructure that global asset managers could invest in, rather than engaging on a project-by-project basis.
Éric Martel, CEO of Bombardier, told reporters on the sidelines of the summit Tuesday that while he regularly engages with global investors, bringing the investment community to Canada sends a stronger message.
“It shows that we’re not just alone,” he said. “It shows our country’s behind us, our resources are behind us … it just also explains what Canada is capable of doing.”
— With files from Kyle Duggan and Catherine Morrison in Ottawa
This report by The Canadian Press was first published Sept. 15, 2026.