
Maxx Bonnefoy’s mortgage renewal couldn’t come sooner.
In 2023, the 37-year-old army veteran and his partner signed a contract to buy a pre-construction home in Tyndall, a village in rural Manitoba. Around the time, he was preapproved for a rate of around 3.99 to 4.5 per cent.
But by the time the property — a four-bedroom, semi-detached house — became ready for occupancy in 2024 and they were able to get a mortgage, rates had gone up dramatically.
The couple decided to lock in a three-year fixed rate at 5.6 per cent, with hopes of getting a lower rate in early 2027.
“I was like: you know what? There’s no going back,” said Bonnefoy, who was working three jobs at the time to support his family. “I’ve already committed to the purchase. I’m not backing out of the deal.”
But as his renewal date nears, Bonnefoy might not get the big break he’s looking for as rates tick up due to larger forces beyond his control.
When interest rates started coming down in 2024, more Canadians turned to shorter fixed-rate mortgages, hoping that rates would fall even further.
For a while, borrowing costs did drop, with the Bank of Canada lowering its policy rate to 2.25 per cent from a post-pandemic peak of five per cent.
But, in recent weeks, fixed rates have jumped by around 25 basis points due to surging energy costs and the AI data centre boom. The U.S. Federal Reserve already hiked its benchmark interest rate, while the Bank of Canada has warned it may have to raise its policy rate if oil prices remain high, which would immediately increase variable rates.
That means some borrowers who took out shorter term mortgages will be renewing at higher rates than they likely expected.
That includes more borrowers than it used to. Data from the Canada Mortgage and Housing Corp. (CMHC) shows a meaningful increase in fixed-rate mortgages of less than five years, and in the last few months interest in variable mortgages has grown.
This trend has CMHC’s chief economist worried, as he expects rates to be higher and more volatile going forward.
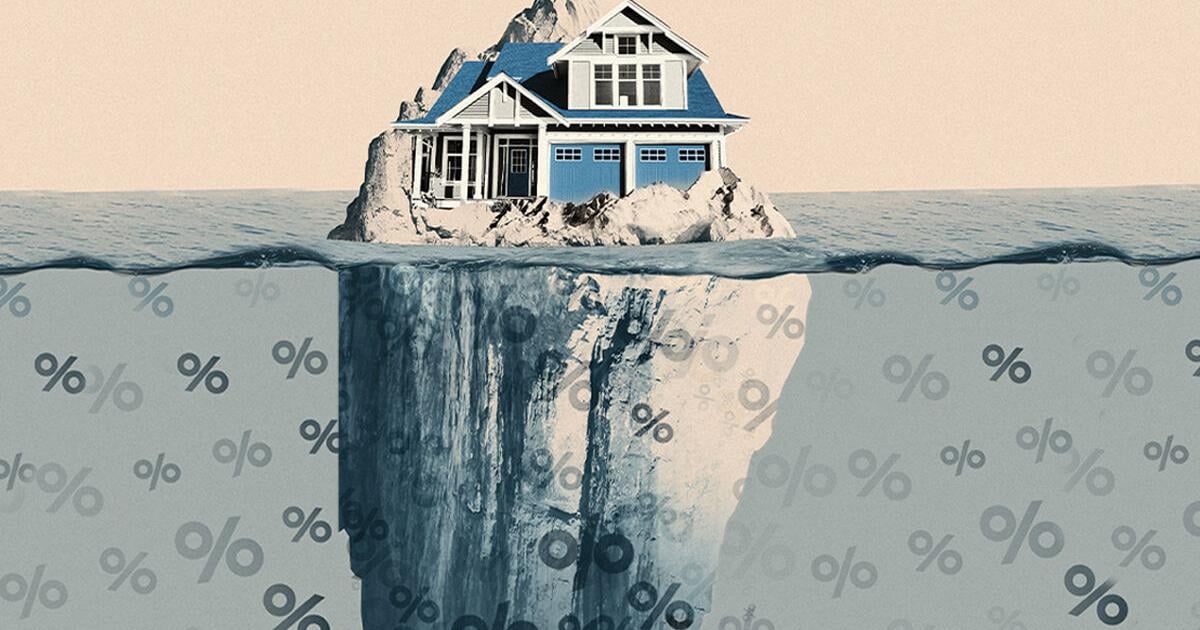
Borrowers renewing their mortgages more frequently are more exposed to “interest-rate risk,” as they are prone to payment shocks that can lead to affordability struggles and even distressed home sales, says Aled ab Iorwerth.
While he’s concerned for individual homeowners, he also fears the ripple effect this can have on the Canadian economy.
“While some of those decisions may have been OK in the last 20 years, I’m just a little bit — I’m not sure what the word is — cautious, nervous, uncertain that maybe the future isn’t what it used to be.”
Why fixed interest rates are rising
While variable mortgage rates are determined by the Bank of Canada’s policy rate, fixed rates are linked to the bond market.
A bond is a loan to the government or a corporation with a rate of return called a yield. When more people want to buy bonds, which are considered a low-risk investment, the bond issuer can offer a lower yield. When fewer people want them, they need to offer a higher yield to attract investors.
When bond yields rise, fixed rates also go up because lenders use bonds to fund mortgages.
Recently, fixed rates have been under pressure, with the 10-year U.S. Treasury yield rising 80 basis points between late February and the first week of September, according to TD Economics.
Part of the increase in yields can be attributed to temporary factors, such as inflation concerns fuelled by the ongoing conflict in the Middle East, said Vikram Rai, senior economist at TD.
Inflation reduces the value of bonds by eroding future returns, leading issuers to raise yields.
“As that uncertainty comes away and inflation comes down, we would expect that long-term bond yields would also see some pressure come off,” he said, adding the U.S. Federal Reserve has begun tackling inflation risk by raising its policy rate in mid-September.
But other factors are “structural,” according to both Rai and ab Iorwerth.
One issue is that, while the U.S. government’s deficit has ballooned, there’s been less demand from global central banks for U.S. government bonds.
“Now we’re in a world where most foreign central banks are satisfied with how much U.S. treasuries they have in their central bank reserves, and they’re diversifying or they’re not expanding their reserves,” said Rai.
Another big force driving yields higher is the rise of AI data centres.
As hyperscalers such as Amazon and Microsoft race to build AI infrastructure, they’ve been borrowing more money through private loans.
With companies issuing more private debt, governments have to offer a higher yield to make their bonds more attractive to investors, said Rai.
Volatility in the U.S. bond market has inevitably spilled over into Canada, resulting in the recent rise in fixed mortgage rates.
“In the last week, fixed rates have jumped by probably 0.15 to 0.25 per cent,” Mary Sialtsis, a Toronto-based mortgage broker, said in an interview on Sept. 22.
Why short-term mortgages bring more risk
As interest rates become more volatile, the burden from rate changes is borne by households more so than lenders, according to a recent report by CMHC.
“In the U.S., they have 30-year mortgages, and so generally what happens is that interest-rate risk is borne more by the financial sector, by the banks,” said ab Iorwerth.
Canadians have long preferred a five-year mortgage. But lately two- and three-year terms have become popular.
“What is now happening in Canada is, because people are moving to short-term mortgage rates, they will be renewing fairly often,” he added, “So more of that interest rate adjustment … is being placed on Canadian mortgage holders.”
A mortgage consumer survey conducted in January by CMHC found that 35 per cent of respondents who renewed a mortgage experienced increased financial pressure due to changes in interest rates.
Meanwhile, 25 per cent of respondents said they had regrets about some of the characteristics of the mortgage they chose.
“Canadians spend more time thinking about mortgage rates,” said ab Iorwerth.
“So they have to become a little bit expert on interest rates, which is tough. They may not have all the information that the banks have to make the best guess about where interest rates are going.”
Gap between fixed and variable growing
There are early signs that borrowers are turning to variable mortgages as fixed rates rise.
Currently, the spread between fixed and the variable rate is around 94 basis points, with the best five-year fixed rate at 4.34 per cent compared to the best five-year variable rate at 3.4 per cent as of Friday, according to Ratehub.ca.
Data supplied by Rates.ca, another rate comparison website, shows that around 29 per cent of total quotes requested by customers in August were for variable mortgages as opposed to fixed.
That compares with 21 per cent in August 2025.
Bonnefoy is among those considering going with a variable mortgage when his renewal comes up next year so he can take advantage of a lower rate.
“At current rates, and depending on which product I choose, the payment amount would probably go down anywhere from $100 to $200” biweekly, said Bonnefoy.
“With the variable rate mortgages, you can lock in at any time as long as that’s in your contract,” he said. Most lenders allow borrowers to switch to a fixed rate without needing to requalify.
But the large discrepancy between rates might be short-lived. Markets are now pricing in higher odds that the Bank of Canada will start hiking its policy rate this year, which would impact variable rates.
“It’s likely that the Bank of Canada will increase the overnight lending rate by a full per cent by the end of 2027, maybe earlier,” said Victor Tran, Rates.ca mortgage and real estate expert.
Housing market, economy at stake
Rate shocks due to the rise of shorter mortgages threaten to further hurt an already cool economy, said ab Iorwerth, especially with Canadian households already carrying high levels of debt.
“You would see more of households’ budgets being taken up by paying interest,” he said, which would lead to “less resources for other forms of consumption or for savings in general.”
Some economists worry that rising rates will also erase recent progress in housing affordability in Canada.
“That’s going to keep a pretty heavy lid on the housing market,” said Robert Kavcic, senior economist at BMO. “You were starting to see some areas where affordability was — it was not back to normal — but it was getting back within the realm of what’s reasonable again.”
Now, Kavcic expects the market will be “stuck for quite some time.”
He said he considers the evolving trends in mortgage preferences as a yellow — not red — light for the economy.
“I wouldn’t say it’s something that’s going to break the economy,” said Kavcic.
“It makes us more rate sensitive. So you might see discretionary spending respond a little bit quicker than it otherwise would.”
Bonnefoy understands that going with a variable rate comes with more risk, as any increases by the Bank of Canada would affect his payments immediately, but “you have to find the savings where you can,” he said.
“The thing I teach my son is that when you make a decision, make sure you look at as much information as you can, inform yourself, and then only worry about things that are in your control,” he said.
“I can’t control the rates,” Bonnefoy added. “I can’t control who’s going to start a war.”
Error! Sorry, there was an error processing your request.
There was a problem with the recaptcha. Please try again.
You may unsubscribe at any time. By signing up, you agree to our terms of use and privacy policy. This site is protected by reCAPTCHA and the Google privacy policy and terms of service apply.
Want more of the latest from us? Sign up for more at our newsletter page.

