
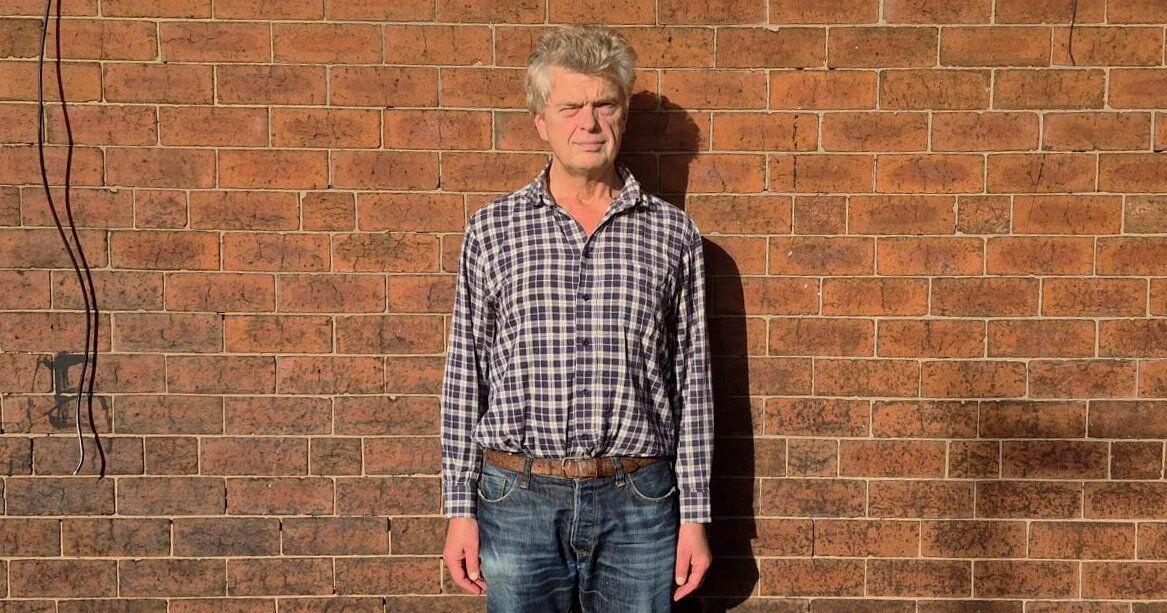
Richard Drake just wanted to buy some alfalfa for his new livestock feed business — two shipping containers’ worth from Dunlea Farms outside Hamilton.
But the U.K. businessman had no idea that the Canadian account he opened while on holiday in Toronto last year could trigger a standard secret bank review of potentially illicit financial activity that CIBC says it can neither confirm nor deny.
Drake closed the bank account 10 months ago after CIBC, he said, refused to wire transfer a payment to the farm to complete the sale. He had been trying to recover his balance — roughly $30,000 — ever since.
“They hold an undisputed balance of $16,948.93 (U.S.) and $8,262.55 (Canadian) belonging to me,” Drake said in late August, “yet refuse to wire the funds to my European/U.K. accounts or provide an operational resolution.”
“I’m over 60,” he told me in a phone interview. “I’ve done international business with banks around the world: Hong Kong, Taiwan, the Netherlands, Germany, U.K. and Dubai. I’ve never experienced anything like this before.”
Why banks can freeze your account without explaining why
When Drake reached out, I wanted to help. I also wanted to understand how and why a Canadian bank could make it so hard for a customer to access their money.
My reporting revealed an opaque, automated world where consumers can accidentally trip wires meant to catch money launderers and terrorists without even knowing it.
“This has caused me massive personal problems,” Drake said, “and effectively frozen my business activity since last November.”
Under federal law, Canadian banks are forbidden from telling customers they’ve tripped wires laid to catch suspicious activity. Disclosure is a federal crime, punishable by up to two years of imprisonment or substantial fines.
“We do not comment on our monitoring and investigation processes,” CIBC spokesperson Stephanie Marcus told the Star in an email. “The delay in this matter is due to factors beyond our control and not indicative of any issue with our processes. We are unable to comment further for privacy reasons.”
CIBC has reason to be cautious. In late 2023, Canada’s financial intelligence agency, FINTRAC, hit the bank with a $1.3-million penalty after an audit revealed it had failed to report suspicious transactions and mandatory incoming cross-border transfers.
Through more than 40 emails and several telephone calls with Drake and a deep dive into the dizzying world of federal and global financial regulation, an explanation emerged.
How FINTRAC’s red flags triggered the freeze
The Financial Transactions and Reports Analysis Centre of Canada (FINTRAC), which sets guidelines and enforces compliance for business transactions, compels banks to conduct ongoing monitoring of customers.
After Drake opened his account, the bank’s federally mandated compliance software started mining global corporate databases, mapping his digital financial footprints.
“You must take enhanced measures and conduct enhanced ongoing monitoring of a client that you have identified as posing a high risk,” FINTRAC’s directives state.
FINTRAC’s Risk Assessment Guidance lists non-resident status and cross-border activity as high risk.
Drake ticked both of those boxes just by opening the account and wiring money to a relative in England shortly after.
The bank’s automated “know your client” audit of Drake would have also uncovered other facts it likely classified as red flags.
On July 14, 2025, shortly before Drake arrived in Canada, the U.K.‘s Companies House public database, which tracks corporate registrations and transfers, shows he was officially appointed director of Greenbourne Trading Ltd. Drake says he bought the “off-the-shelf” registered company to save time and money. The alfalfa purchase was meant to be an early test product as he didn’t attain full sole legal control of the company until March 2026.
When contacted by the Star, Dunlea Farms confirmed that it had invoiced Richard Drake roughly $17,000 (U.S.) for the purchase of the alfalfa feed, but the order was never fulfilled.
To Richard Drake, Greenbourne was a harmless, dormant shell, off-the-shelf company with no trading history. To CIBC’s automated risk engine, however, it was a cluster of red flags, though the Star found no evidence of any illicit activity.
Greenbourne was incorporated by an agent who held thousands of corporate appointments (red flag). It sat dormant for nearly four years (red flag) before Drake assumed directorship, and its filing address changed (red flag).
Drake tried to wire money to a family member
As the flags piled up, the bank, adhering to federal regulations, never shared its concerns with Drake and he never had an opportunity to explain. When Drake attempted to pay for his alfalfa using his personal account, the bank’s compliance algorithm did exactly what it is programmed to do: it locked the doors.
Drake told CIBC that he needed to convert a portion of his balance into roughly $16,000 (U.S.) for a wire transfer purchase of agricultural goods. The bank allowed him to open a U.S. currency account and converted his funds, but later told him, Drake says, it could not wire the funds to another Canadian bank.
Drake then attempted to wire the money to a family member in the U.K.
“After I returned to the U.K., I was called twice by the teller with some security questions, which I answered,” he said. “I was then called back and told that CIBC declined to make the transfer and returned the money to my account.”
Frustrated, Drake instructed CIBC to close both accounts and transfer his balance to his U.K. bank.
Instead of executing the electronic transfer, CIBC issued a formal “divestiture letter,” terminating its relationship with Drake. He also lost access to his mobile banking app and says his emails to CIBC went unanswered for roughly a month.
Fed up, Drake appealed to CIBC’s CEO, Harry Culham in January. A senior manager responded to Drake by email and told him the bank couldn’t electronically transfer his money and that Drake would have to provide a notarized ID verification before it would issue a physical bank draft.
Drake quickly complied with this request.
Five months later, in May, CIBC mailed the USD and CAD bank drafts to Drake’s home in York, England. His home bank, however, told him that it was phasing out foreign paper instruments and could not clear them. He opened an account at another U.K. bank, which instructed him to mail the cheques to their clearing department where, he said, they were subsequently lost.
Drake immediately updated CIBC and asked for the draft to be reissued or his money to be wired to him. He said he submitted a notarized affidavit the bank had requested vowing he not cash the draft if it turned up.
In August, after CIBC told him it was “still reviewing” his request, he filed a complaint with the Ombudsman for Banking Services and Investments (OBSI), the Financial Consumer Agency of Canada and emailed the Toronto Star for help.
How his 10 month ordeal finally ended
Drake also emailed the ministries of international trade and agriculture in Ottawa.
Cedric Gigoux, acting deputy director of ministerial correspondence for the ministry of agriculture, forwarded the file to the finance ministry, which oversees federal banking legislation.
In late September, some 10 months after Drake’s foray into Canadian banking went pear shaped, CIBC returned all of his money — by wire transfer.
“It’s resolved now,” Drake wrote in an email in late September, adding he hoped I would still write about the situation.
He also said he ended up procuring a shipment of alfalfa — from an American farm on spec.